What Credit Karma Actually Does
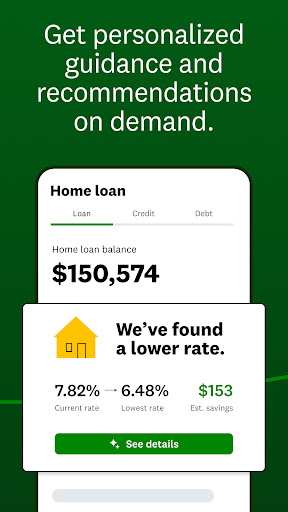
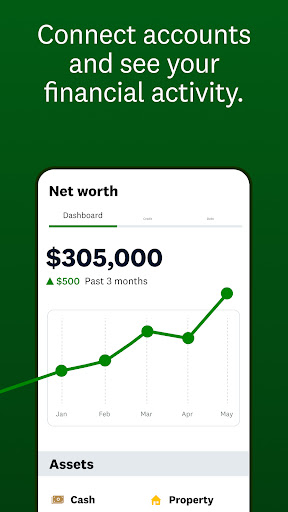
Credit Karma is a free finance app that pulls your credit scores, tracks spending across linked accounts, surfaces personal loan and credit card offers, and now includes banking (Spend and Save accounts) and car insurance comparisons. It’s built for people who want a free, ongoing view of their credit health rather than a one-time score check. The app is aimed at anyone from credit-builders with thin or damaged credit files to established users who just want alerts on score changes, late payments, or better interest rates.
Where It Genuinely Helps
The strongest evidence for this app comes from users who started with poor credit. One reviewer described joining with a 524 score, following Credit Karma’s suggestion to get a starter card, using it for a single recurring bill on autopay, and years later owning a house with credit cards carrying $11,000 limits. That’s the core use case working as intended: a free on-ramp to building credit history with concrete, actionable suggestions rather than vague advice.
Another user who initially blamed the app for login failures found, after actually contacting support, that the real issue was a blocked verification text on their end — support walked them through it and fixed it. When the underlying systems work and support engages properly, people do get resolutions.
The Score Update and Login Problems
The most common serious complaint is about broken core functionality. One reviewer reported their credit score simply stopped updating for months, with the app repeatedly showing a message that the score couldn’t be refreshed and old data was being displayed. For an app whose entire value proposition is timely credit monitoring, a stale score isn’t a minor bug — it undermines the product’s basic purpose. Others describe registration and login loops: the app rejecting phone numbers, throwing ‘too many tries’ errors, then locking users out with an ‘unable to contact Credit Karma’ message that reportedly has no easy fix.
Offers and Loan Matching Don’t Always Deliver
Multiple reviews describe frustration with the loan and card marketplace. Users report being funneled through lengthy applications only to get rejected due to debt-to-income ratio, or approved for rates and payments no better than the debt they were trying to consolidate. One reviewer specifically warns against the OpenSky card recommendation, saying they never received the card but were billed a $2 monthly fee anyway. Since Credit Karma is compensated by these third-party advertisers, it’s worth remembering the app isn’t a neutral advisor — it doesn’t appear to vet every offer it surfaces.
Customer Support Is Inconsistent
Support quality comes up repeatedly, in both directions. When it works, as with the texting issue above, it can solve real problems. But another reviewer, specifically referencing the banking product where Credit Karma holds actual funds, called support difficult to reach and poorly trained — a bigger concern once money, not just data, is involved.
Who Should Actually Download This
If you want free credit monitoring and are starting from a low score or thin file, this app has a track record of helping. If you’re chasing loan consolidation or rely on real-time score accuracy, be prepared for possible stale data and underwhelming offer approvals, and don’t treat every recommended card as vetted.